OneBlinc - Financial tools

Screenshots
Details
- Rating
- 672.00 reviews
- Version
- 7.12.0
- Developer
- OneBlinc
Analysis by Norviv
I approached OneBlinc as a practical finance app rather than something I would open for entertainment. Its purpose is straightforward: help users access earned wages through a linked account when waiting for the usual payday is inconvenient. That makes the first impression easy to understand, especially if a surprise bill, transport cost, or grocery purchase arrives at an awkward time.
After using it as a short-term money-management tool, my view became more nuanced. The app can be useful when it fits a specific cash-flow problem, but its lasting value depends on whether you treat it as an occasional bridge instead of a permanent substitute for budgeting. I found that distinction more important than the polished simplicity of the basic idea.
How OneBlinc fits into everyday cash flow
OneBlinc is a free finance app from OneBlinc, available for users on Android starting with version 7.0 and above. It is rated for Everyone, and its current version is 7.12.0. The app has reached over 100 thousand installs, with an average rating of 4.6 from about 4.8 thousand ratings, so it has already attracted a meaningful audience without feeling like an obscure experiment.
The central experience is built around accessing wages through a linked account. In practical terms, I see it as a tool for timing rather than extra income. It does not make a tight budget healthier by itself; it gives you another way to handle the gap between money becoming available and a payment becoming due.
That difference matters. If I use the app to cover a one-off timing problem and then return to my normal spending pattern, it can be helpful. If I use it every pay cycle to make the month reach the end, the convenience starts hiding a deeper problem. The app is strongest when it solves a temporary mismatch, not when it becomes part of a routine that keeps expenses permanently ahead of income.
The first-week appeal is immediate and practical
During the first week, the main attraction is how quickly the idea makes sense. I do not need to learn a complicated investing system, compare financial products, or build a detailed plan before understanding the benefit. The focus is narrow: connect the relevant account and see whether accessing wages earlier suits the situation.
That simplicity is especially useful for someone who has never used an earned-wage tool before. The app’s finance category can sound broader than the actual job it performs, but I found its focused purpose easier to evaluate than an overloaded money app that combines budgeting, investing, credit monitoring, and banking in one place.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
A realistic example would be a worker whose regular pay arrives after a utility bill, a necessary prescription, or a commute expense is due. Instead of putting that cost on a high-interest card or asking someone for help, the person may consider using OneBlinc to manage the timing. That does not remove the expense, but it can reduce the pressure created by the calendar.
My first useful tip is to decide the repayment plan mentally before requesting access. I would ask myself which upcoming income will absorb the amount and what other payment might be squeezed as a result. This small pause prevents the app from feeling like free spending money. It also turns the experience into a deliberate cash-flow decision rather than an impulse response.
The app is also easier to judge when I start with a specific need instead of browsing without a purpose. I would not install it simply because early wage access sounds reassuring. I would install it when I can name the timing problem I am trying to solve and understand how the linked account fits into that process.
What makes the first use less effortless than it sounds
The phrase “linked account” is important. The experience depends on connecting the financial account that the app uses for its wage-access process, so the setup is not the same as opening a calculator or a basic expense tracker. I would take extra care to check that the account is the correct one and that I understand where funds are expected to arrive.
That is also where some users may feel friction. Financial apps require more attention than casual apps because a mistake in account selection, timing, or personal details can have consequences beyond an annoying setup screen. I would avoid rushing through the onboarding process while distracted, and I would read each confirmation rather than tapping through automatically.
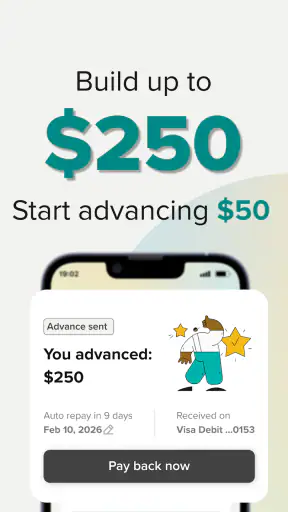
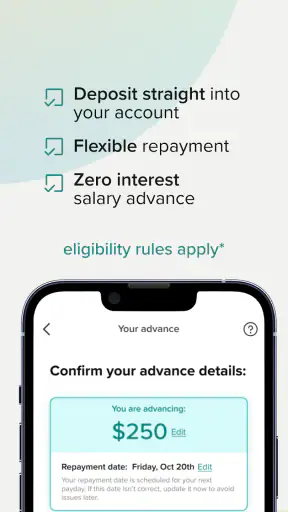
Another point I would keep in mind is that access to wages should not be confused with unlimited access to every dollar I expect to earn. The store summary describes access of up to 250 dollars directly to a linked account, but the meaningful question for an individual user is what amount is actually available in their own circumstances and when it can be delivered. I would check the in-app terms and eligibility details before planning around the money.
That is one of the app’s less obvious trade-offs: its headline benefit is simple, while the personal result depends on account connection, wage information, timing, and the user’s own situation. The interface may make the action feel quick, but a quick action can still have a long effect on the rest of the pay period.
Month-to-month value depends on discipline
After the novelty fades, OneBlinc becomes less about discovery and more about whether I genuinely need its function again. A finance app earns a lasting place on my phone when it helps me make better decisions repeatedly, not merely when its first use feels convenient. Here, the recurring value is conditional.
For someone with occasional income-timing problems, the app can remain useful as a backup. It may be worth keeping available for an unexpected expense that cannot reasonably wait. In that role, I would think of it like a financial emergency tool: present when needed, but not something I expect to use automatically every month.
For someone whose bills regularly arrive before payday, the app may provide short-term relief while leaving the underlying pattern unchanged. That can create a cycle in which the next pay period starts with less flexibility because part of the available income has already been used. In my opinion, this is the most important long-term caution and the clearest reason not to judge the app only by how helpful it feels on a difficult day.
I found a simple monthly check useful: after using the app, compare the next pay period’s essential bills with the money that will remain available. If the same gap appears again, the right next step may be changing bill dates, revising the budget, building a small buffer, or speaking with the relevant provider. OneBlinc can help with timing, but it should not be the only response to a recurring shortfall.
A second non-obvious use case is planning around irregular expenses rather than everyday wants. A vehicle repair, school-related cost, or necessary household replacement is easier to evaluate than frequent small purchases because I can identify the exact reason for the withdrawal and the income that will cover it. That makes the decision more accountable and reduces the risk of treating early access as an invisible spending allowance.
I would also keep a personal note of each use, including the reason and the expected effect on the next pay period. This is not a feature claim about the app; it is a workflow I recommend because the convenience of wage access can make separate withdrawals blur together. A short record helps reveal whether the tool is solving rare timing problems or becoming part of ordinary spending.
Where it compares well with familiar alternatives
Compared with a credit card, OneBlinc may feel more directly connected to earned income and a specific cash-flow need. A credit card can remain available for broader purchases, but it can also encourage a balance to linger and accumulate costs depending on the account terms. I prefer the narrower purpose here when the need is genuinely tied to a near-term wage gap.
Compared with overdraft protection, the app may offer a more intentional step before a payment fails or an account falls below zero. However, overdraft arrangements vary widely, and users should compare the actual timing and terms rather than assuming one option is automatically cheaper or safer. The best choice depends on the payment deadline, the account balance, and how soon income is expected.
Compared with a traditional budgeting app, OneBlinc is not the better choice if my main goal is to categorize spending, set long-term targets, or understand where money disappears. A budgeting tool is more appropriate for diagnosis and planning. OneBlinc is more focused on access and timing, so I would use it alongside a budget rather than expecting it to replace one.
Compared with borrowing from friends or family, the app offers a more private and structured route for a person who qualifies and is comfortable linking an account. On the other hand, personal borrowing may be more flexible in some situations, while the app’s process and availability are tied to its own requirements. I would not assume that convenience makes it the right answer for every emergency.
The practical lesson is that OneBlinc occupies a narrow middle ground. It is more targeted than a general bank account, less suitable for long-term planning than a budget tracker, and potentially less open-ended than a credit product. That specialization is a strength when the problem matches it and a weakness when the user expects a complete financial-management system.
Maintenance is light, but financial attention is not
The app does not need to become a daily habit to be useful. In fact, I think opening it constantly would be a warning sign unless I am checking a specific transaction or timing issue. Its maintenance burden is relatively low in the sense that the core purpose is clear, but keeping the linked account information accurate and understanding each transaction still requires attention.
I would review the connected account whenever my banking setup changes, especially after switching accounts or changing the way wages are deposited. I would also avoid assuming that a previous successful use guarantees the same result in a different pay period. Financial circumstances change, and an old expectation can be more dangerous than an unfamiliar screen.
My third practical insight is to separate “available now” from “safe to spend.” Those phrases may feel similar when money is tight, but they are not the same. Before using an early wage option, I would reserve enough for rent, utilities, food, transport, and any automatic payments that will arrive before the next income becomes available. This mental separation is more valuable than simply knowing the maximum amount the app can provide.
There is also a maintenance habit that costs nothing: remove the app from the decision process when the need has passed. I would not open it just because I have access to it. Keeping a financial emergency tool available is reasonable; building a reflex around it is not. The strongest long-term relationship with this kind of app is controlled and occasional.
Users should also consider privacy and security in a practical way. Because the experience involves a linked financial account, I would use a secure device, keep the operating system updated, and avoid completing account-related actions on a shared phone. These are sensible precautions for any finance app, but they matter more here because the app is connected to real money movement.
Sources of fatigue and frustration
The biggest source of fatigue is the possibility that a quick solution becomes a repeated obligation. The first withdrawal can feel like relief, while the next pay period can feel narrower. If I need the service repeatedly for groceries or ordinary bills, I would stop and reassess rather than celebrating the fact that the app keeps solving the same problem.
Another source of frustration is expectation management. The store summary presents a clear upper limit of up to 250 dollars, but a maximum is not a promise that every user can access that amount whenever they want. I would not build a bill-payment plan around the highest possible figure. I would treat any available amount as conditional until it is clearly shown for my account and situation.
The linked-account requirement can also become tiring if my financial setup is complicated. Someone with several accounts, changing deposits, or irregular income may have to think more carefully about which account is relevant. In that situation, the app may still be useful, but the convenience is reduced because the surrounding financial organization becomes part of the task.
I would skip OneBlinc if I am looking for a full banking replacement, a long-term debt strategy, investment guidance, or detailed spending analysis. I would also skip it if I already have a stable emergency fund and no need for early wage access; adding another financial tool can create unnecessary complexity. Finally, if I know that easy access makes me spend more, a less immediate alternative may protect my budget better.
Some users may prefer a bank feature already built into their main account because fewer connections and fewer apps can make money management easier. Others may prefer a credit product with clearly understood terms for a larger planned expense. The right comparison is not “which app sounds fastest?” but “which option creates the least harmful repayment pressure for this particular need?”
Who will get lasting value from it
I think OneBlinc suits workers who occasionally face a mismatch between when wages are earned and when essential expenses are due. It can also suit people who want a focused tool rather than a large financial dashboard, provided they are comfortable reviewing the linked-account process and thinking ahead about the next pay period.
It is less suitable for anyone hoping to increase their income, erase debt, or make an unstable budget feel permanently comfortable. Early access changes timing, not the total amount earned. That sounds obvious, but it is easy to forget when an urgent payment is in front of me and the app offers a quick path through it.
The Everyone content rating makes the app broadly approachable from an age-classification perspective, but that should not be mistaken for financial simplicity. Younger or inexperienced users may still need a clear understanding of income, bills, account balances, and repayment timing before using any wage-access service. The interface can be accessible while the decision remains serious.
OneBlinc’s free price also lowers the barrier to trying it, but “free” should not end the evaluation. I would still examine the in-app conditions attached to any transaction and compare the overall effect with alternatives. A no-cost download is not the same thing as a no-consequence financial decision.
My long-term verdict after the novelty fades
OneBlinc earns a place on my phone as an occasional financial safety tool, not as a permanent part of everyday spending. I like its focused purpose, its straightforward appeal, and the way it addresses a real problem that general budgeting apps do not solve: the uncomfortable gap between earning money and receiving it.
At the same time, I would only recommend it with a boundary attached. Use it for a clearly identified timing issue, know which future income will absorb the amount, and watch for repetition. If the same withdrawal becomes necessary every month, the app is no longer merely helping with timing; it is becoming part of the budget’s structure, and that deserves a more serious review of expenses and alternatives.
With the current version 7.12.0 and a strong average rating, OneBlinc appears to have found an audience that values this focused approach. My own recommendation is positive but selective: try it when early wage access directly matches your need, keep your expectations below the maximum, and maintain a separate plan for recurring expenses.
The lasting value is not in using OneBlinc more often; it is in using it thoughtfully enough that you need it less often. For occasional cash-flow pressure, that makes it a useful finance app. For chronic shortfalls or broader money management, I would choose a budgeting plan, a bank-based solution, or professional financial guidance instead.
Frequently Asked Questions
01What is OneBlinc, and what financial tools does it provide?
OneBlinc is a financial app designed to help eligible users manage short-term cash-flow needs and everyday money more conveniently. Depending on your eligibility and location, its tools may include access to paycheck advances, a spending account, budgeting features, credit-building support, and other financial services. Available products, limits, fees, and conditions can vary, so review the details shown in the app before accepting any offer.
02Who can use OneBlinc, and what information is required to sign up?
OneBlinc is generally intended for users who meet specific eligibility requirements, such as being an adult resident of a supported area and having qualifying income or employment information. During registration, the app may request personal identification details, banking information, and permission to verify income or account activity. Approval is not guaranteed, and requirements can change according to the product and the applicant’s circumstances.
03Does OneBlinc charge fees or interest for its financial services?
The cost of using OneBlinc depends on the particular service, membership option, advance, or account feature selected. Some products may involve subscription charges, expedited-transfer fees, or other costs, while terms can differ between users. Before confirming a transaction, carefully examine the displayed fee, repayment amount, due date, and applicable disclosures so you understand the total cost rather than relying only on promotional descriptions.
04How do paycheck advances and repayments work in OneBlinc?
If you qualify for a paycheck advance, OneBlinc may allow you to access part of your expected income before your regular payday. The amount and delivery speed depend on verification, account history, and the option selected. Repayment is typically scheduled around your incoming paycheck or another agreed date. Make sure sufficient funds will be available, because a repayment can affect your budget and may result in additional charges under the applicable terms.
05Is OneBlinc safe to use, and should it replace a bank or financial adviser?
OneBlinc uses account verification and security measures intended to protect user information, but no online financial service is completely risk-free. Download the app only from an official store, use a strong password, and review permissions and privacy terms before connecting accounts. OneBlinc can be useful for specific short-term financial needs, but it should not automatically replace a traditional bank, emergency savings, or professional financial advice.


